Smarter Engagement.
Higher Recoveries.
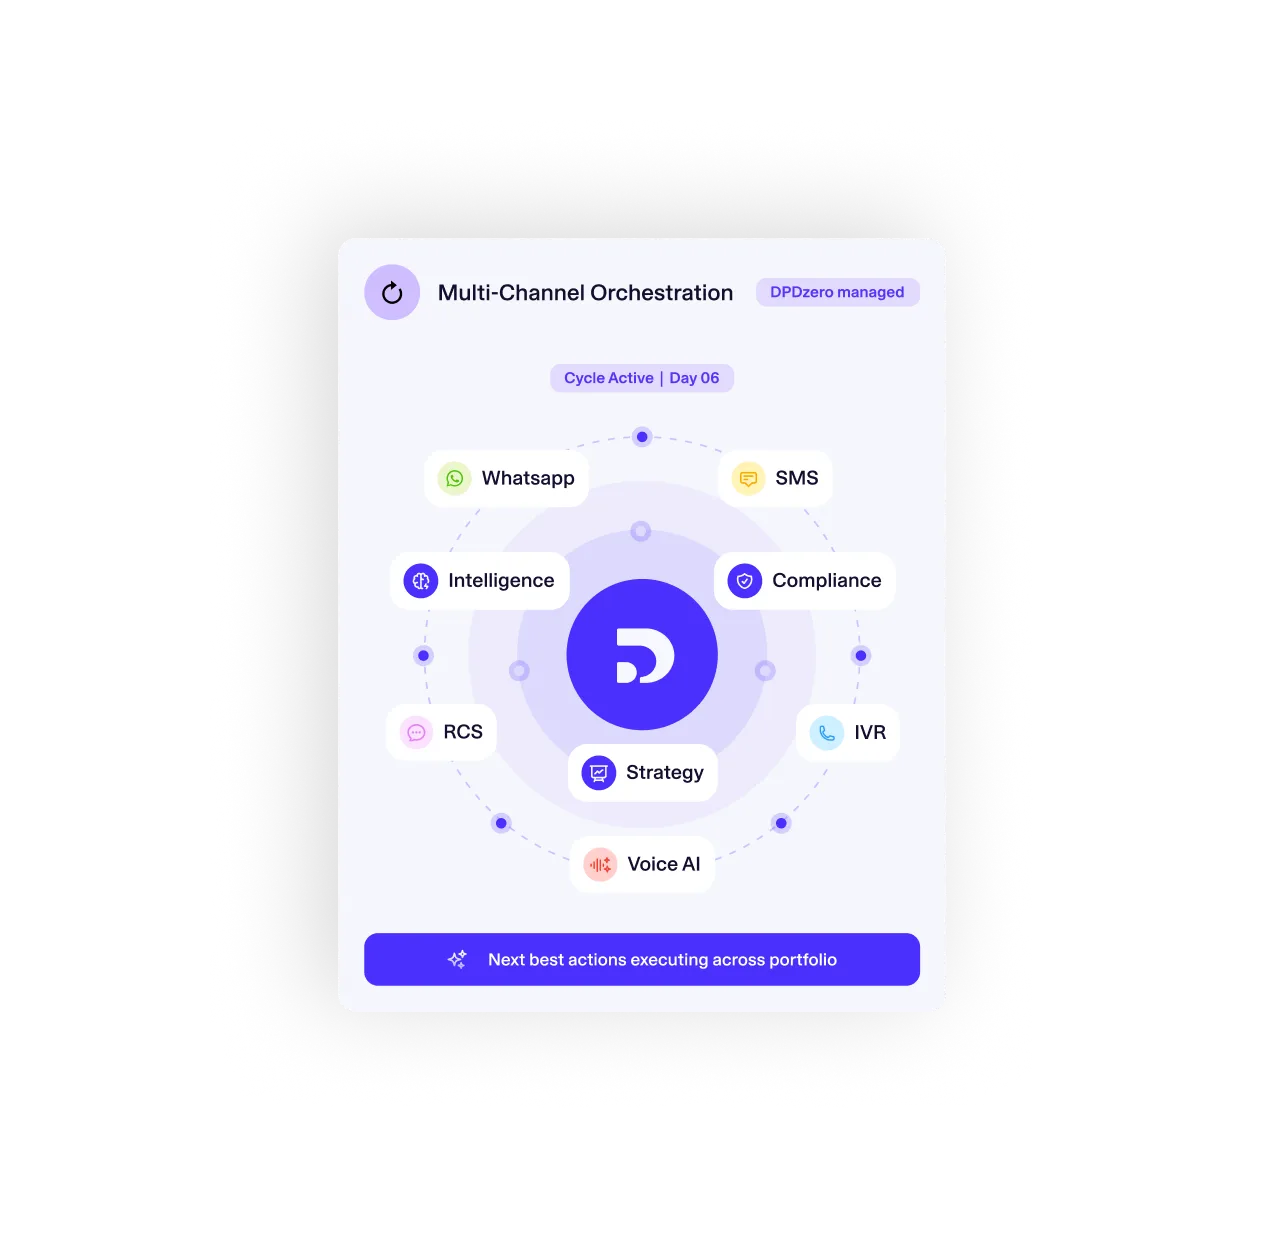
Orchestrate every borrower interaction across WhatsApp, SMS, RCS, IVR, and Voice AI with intelligence - driving higher engagement, lower collection costs, and better recovery outcomes.
Coverage on Day1
Channels, 1 Platform
Indian Languages


Outreach without Intelligence Doesn’t Scale Recoveries
As portfolios grow, delinquent accounts outpace calling team capacity. Unengaged accounts are more likely to roll forward, increasing delinquency and recovery costs.

Campaign over Conversations
Every borrower receives the same reminders regardless of intent, repayment behaviour, or likelihood to engage.

Channels Operate in silos
WhatsApp, SMS, IVR, and Voice calls run independently, with no shared context or coordinated journey.

Rules don’t learn
Static workflows can't adapt to borrower behaviour, leading to repeated outreach and missed recovery opportunities.

Engagement isn’t Intelligence
Message delivery, opens, and clicks generate data - but without AI decisioning, those signals rarely improve the next interaction.

Digital doesn’t scale without automation
Managing millions of borrower interactions manually creates operational complexity, inconsistent execution, and rising collection costs.
Five Channels. One Borrower Context. Running in Parallel.
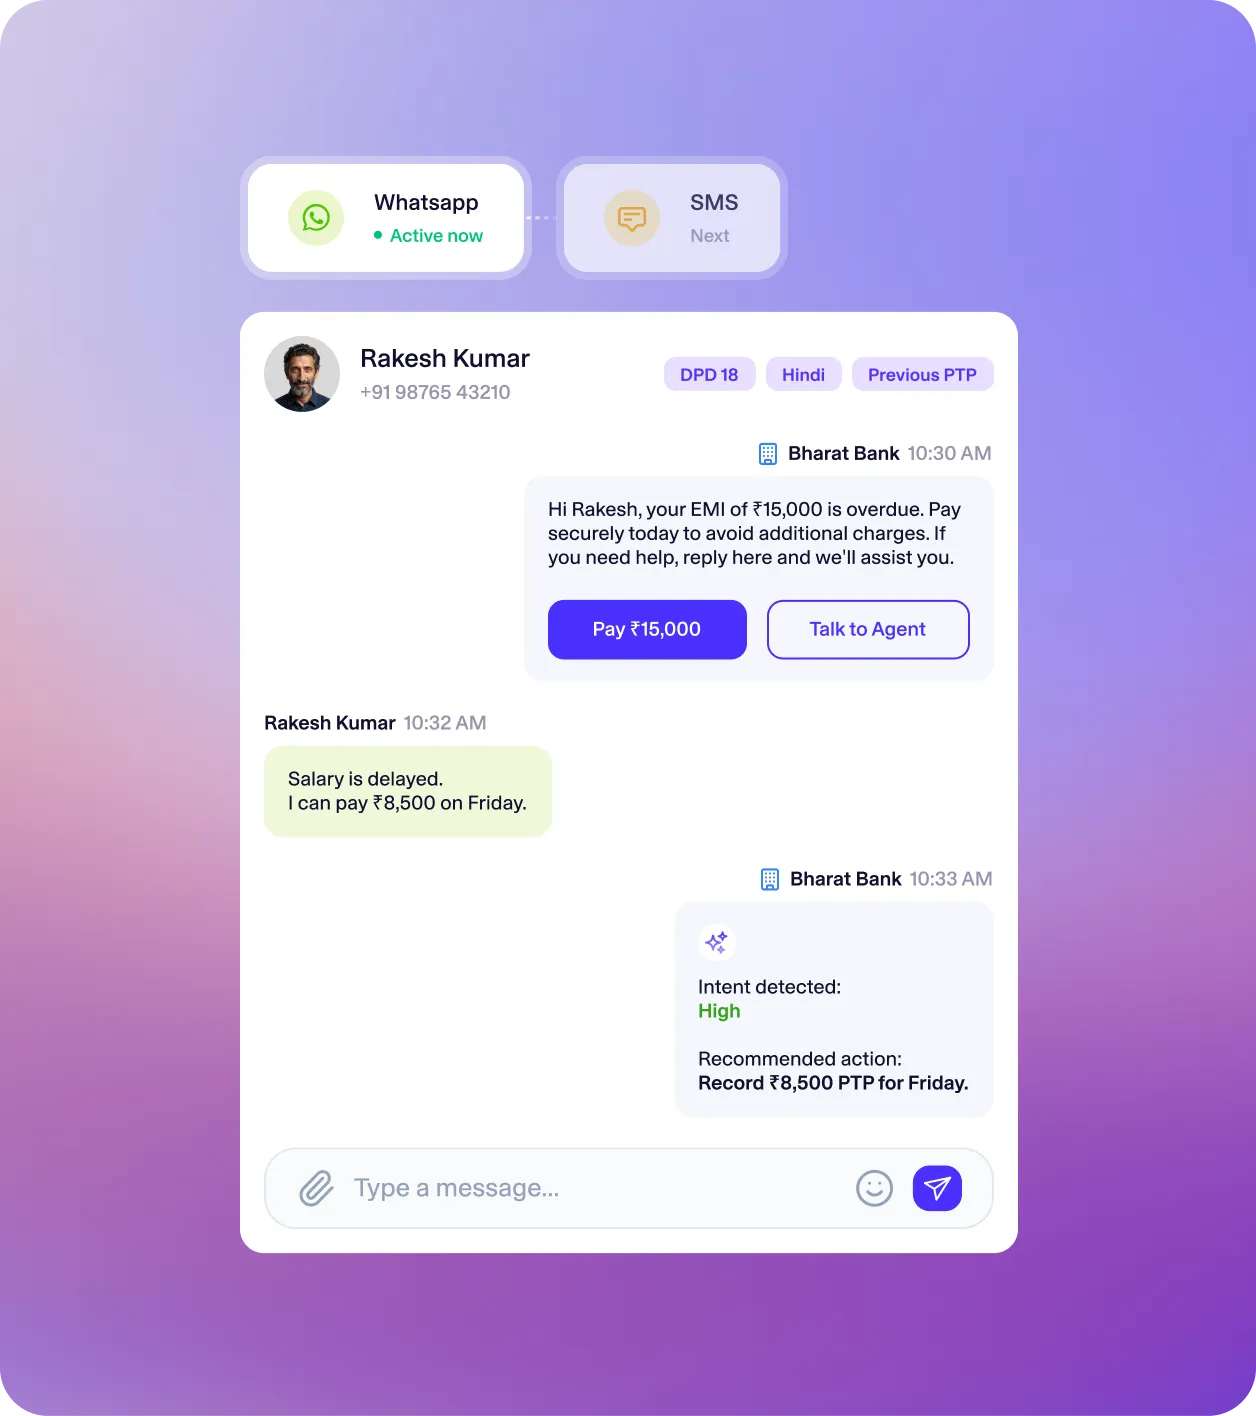
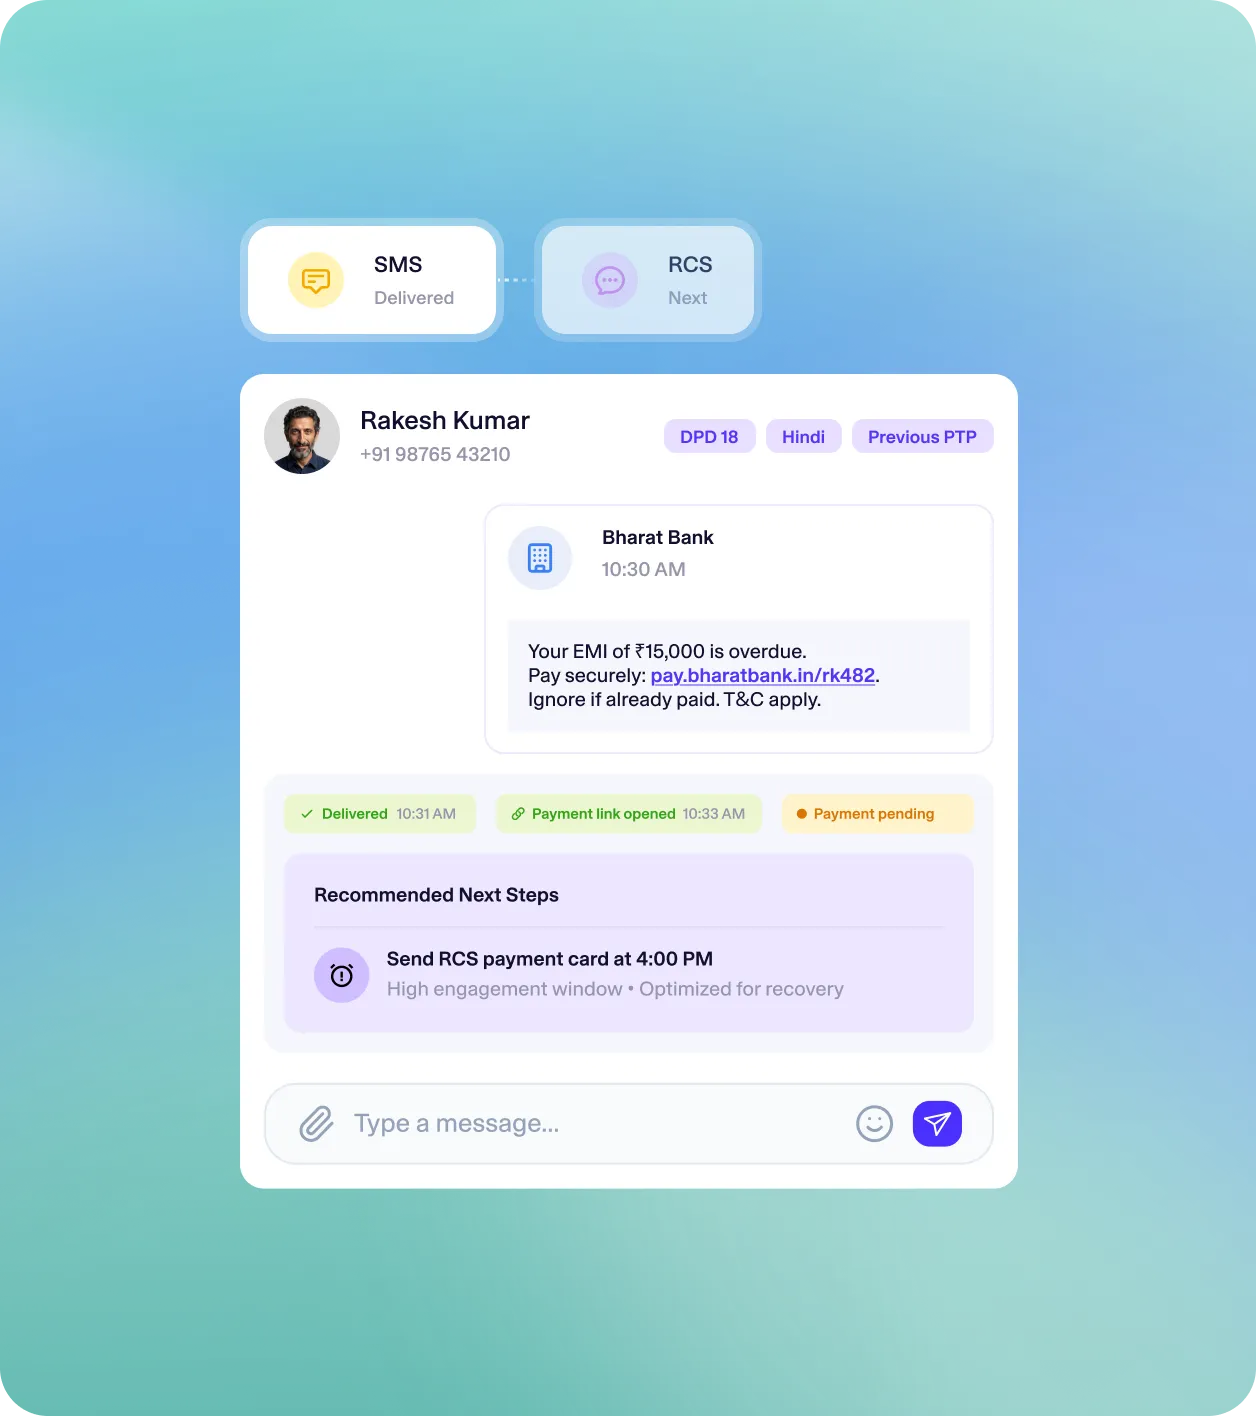
Every interaction response from the borrower guides the next best action without ever losing the borrower context in real-time leading to higher engagement and maximum recovery.
SMS
RCS
IVR
Voice AI
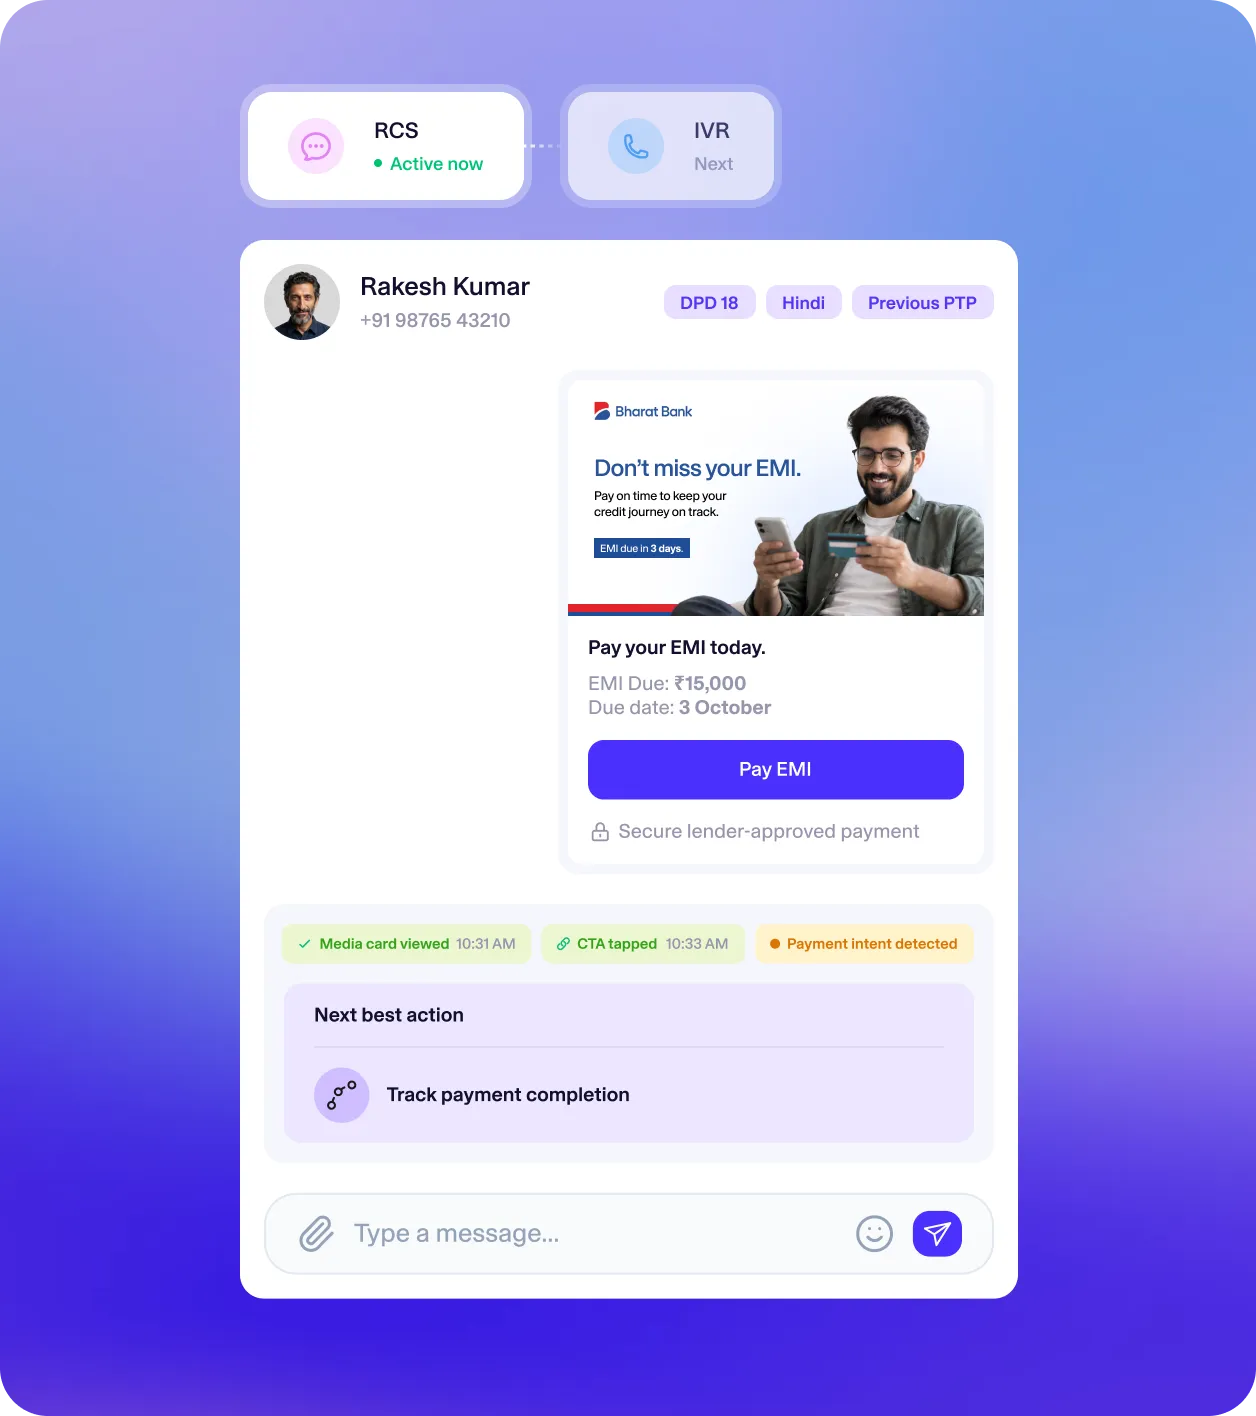
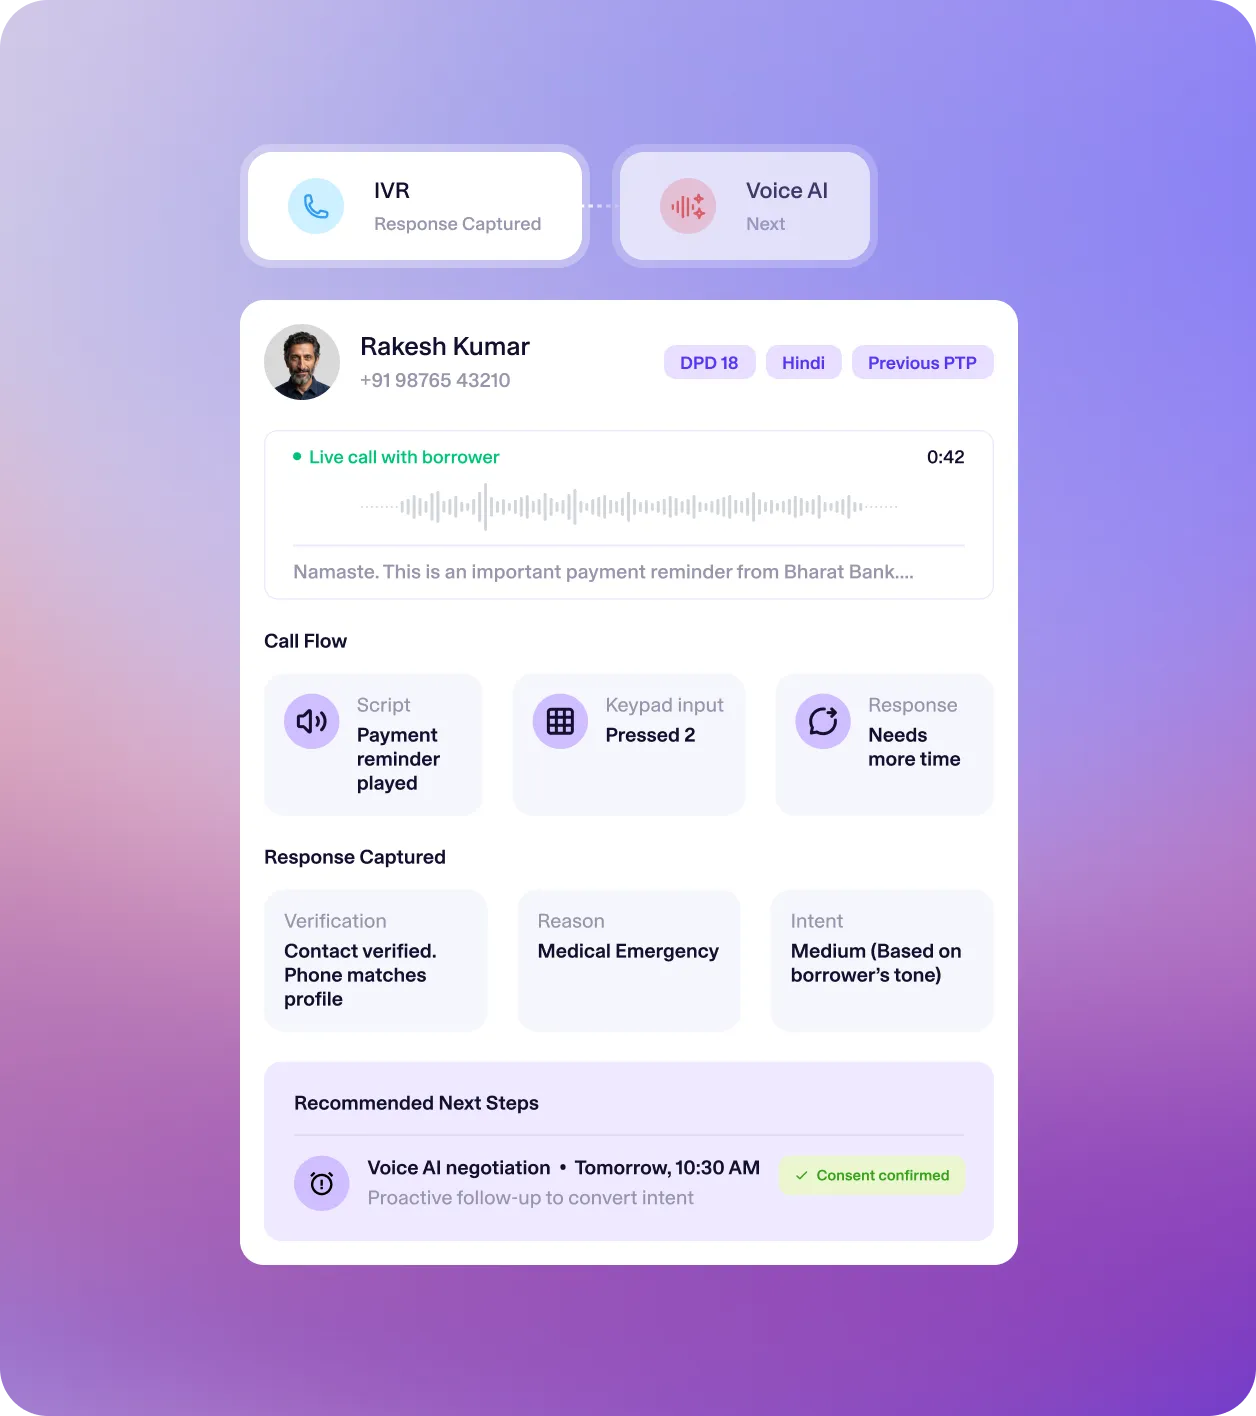
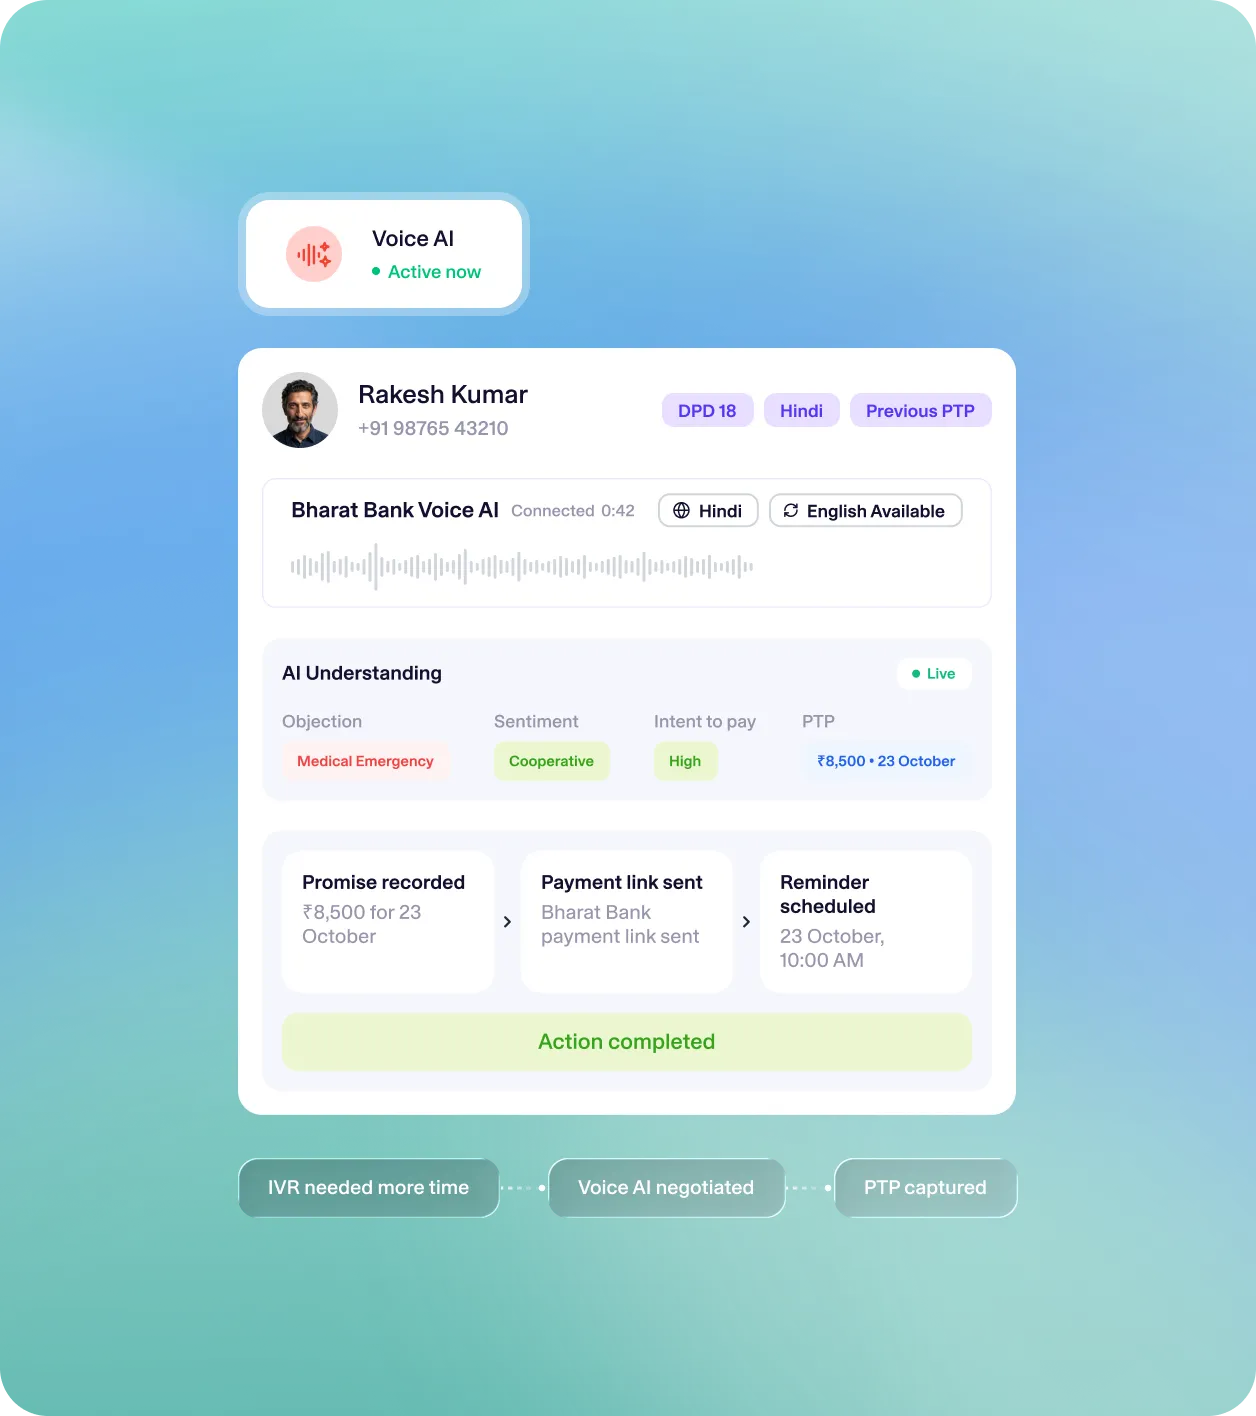
Every portfolio is different.
Every borrower is unique.
We figure out who needs what and when
Most lenders blanket their portfolio with telecalling from day one. It's expensive, it's operationally intensive, and it treats every borrower the same. The difference lies in figuring out the right channel, right message and right time for each borrower.
Score before you send
Every account is cohorted on risk and propensity as soon as allocation arrives, using payment history, bureau signals and past contact behaviour with AI based decisioning.
Choosing the Best Outreach Channel
Each cohort gets its own action plan. A high-propensity borrower may never need more than a WhatsApp; a silent one moves up the outreach plan faster.
Gathering Borrower Intelligence in real-time
Non-delivery, silence, a broken PTP or a detected dispute escalates the account to the next best channel for faster resolution.
Every signal feeds for next collection cycle
What worked on this cohort this cycle reshapes the next cycle's outreach strategy. The sequence gets smooth and efficient with every repeat cycle
Five Channels.
Across Delinquencies.
Early delinquency is a reminder problem. Late delinquency is a negotiation problem. The channel mix shifts accordingly - the methodology doesn't.
Make paying easier than ignoring.
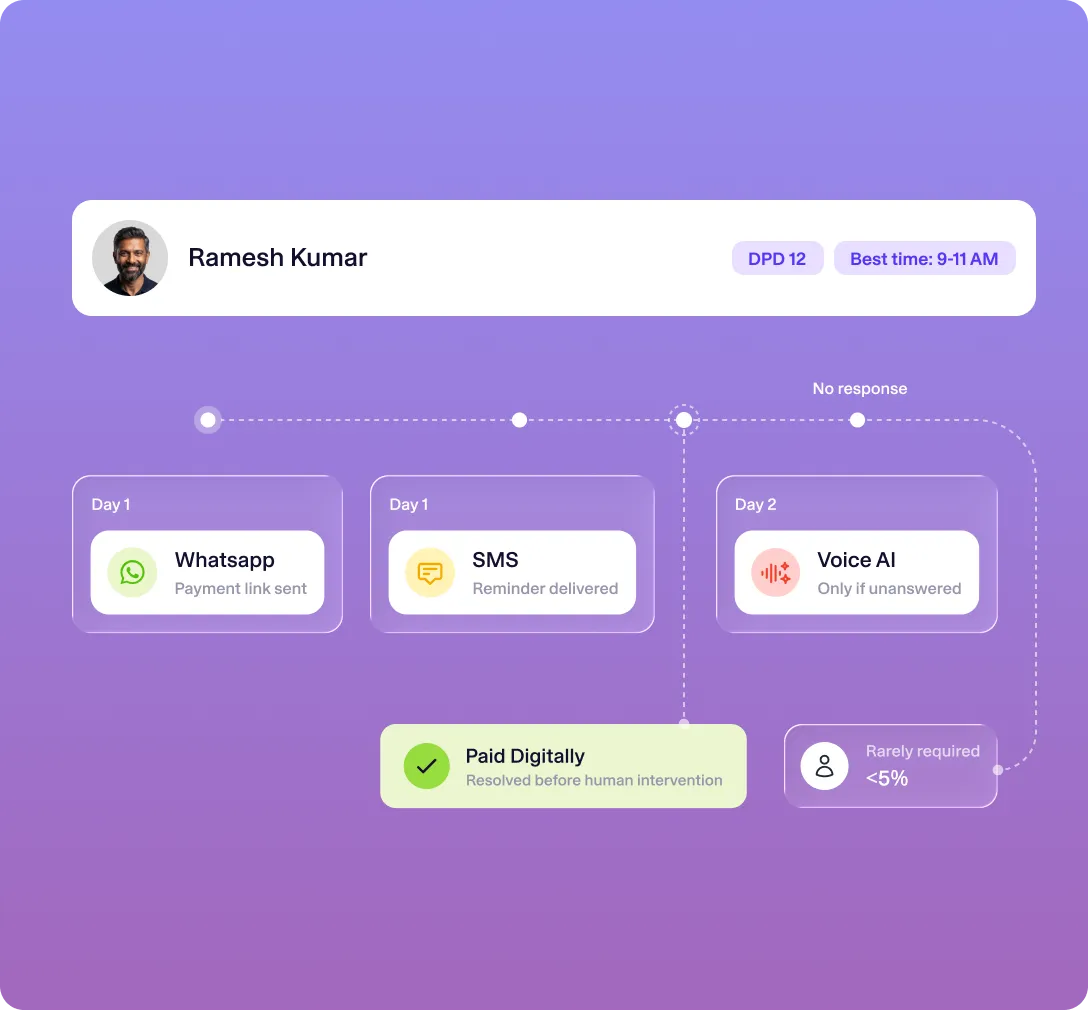
Most early delinquency is friction, not distress. The sequence stays almost entirely digital; a payment link in the right thread at the right hour resolves the majority before anyone picks up a phone.

Objective
Leads with
Voice AI
Human Advisors
Find out what actually happened.
By now it is not forgetfulness. The sequence shifts toward conversation, because the lender needs a reason — cash-flow gap, dispute, or disengagement — before it can structure a way back.
Objective
Leads with
Voice AI
Human Advisors
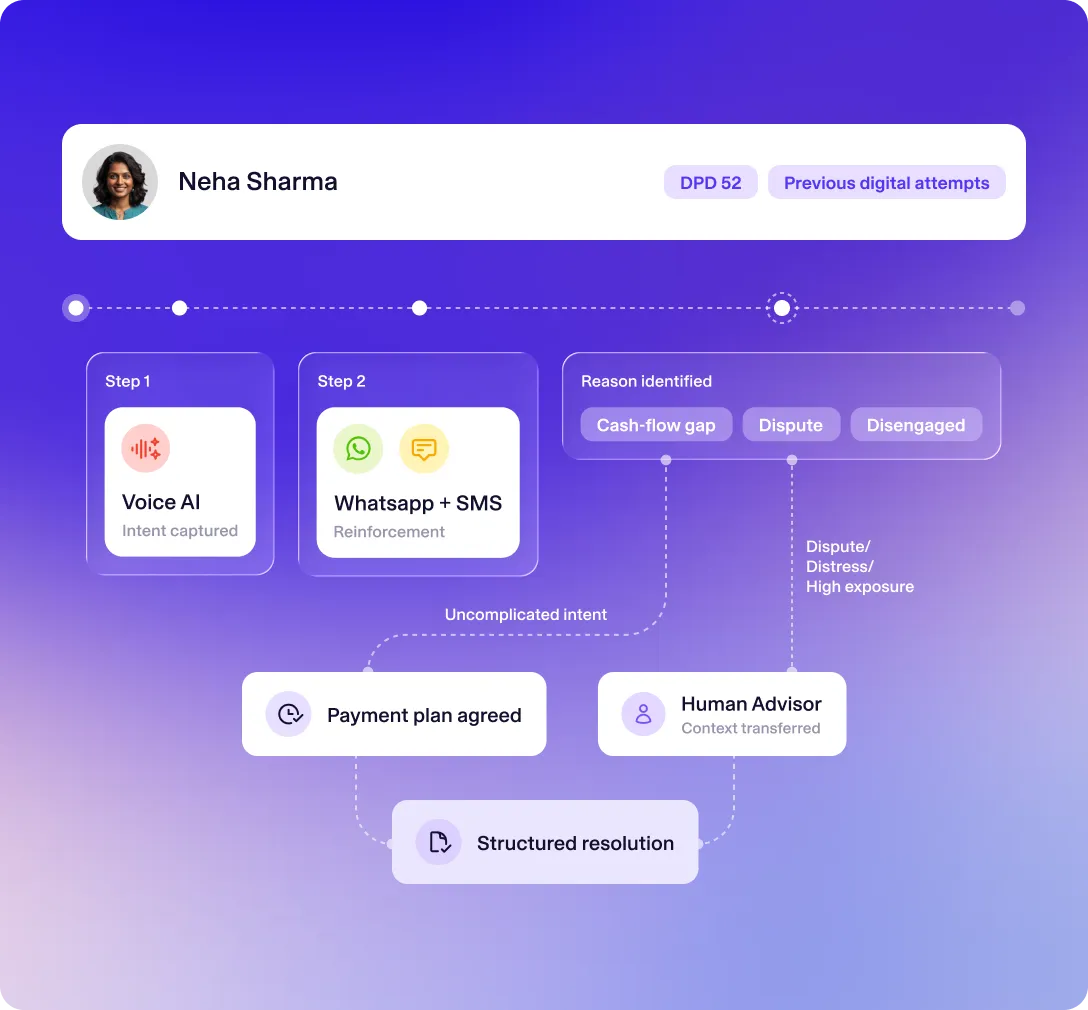
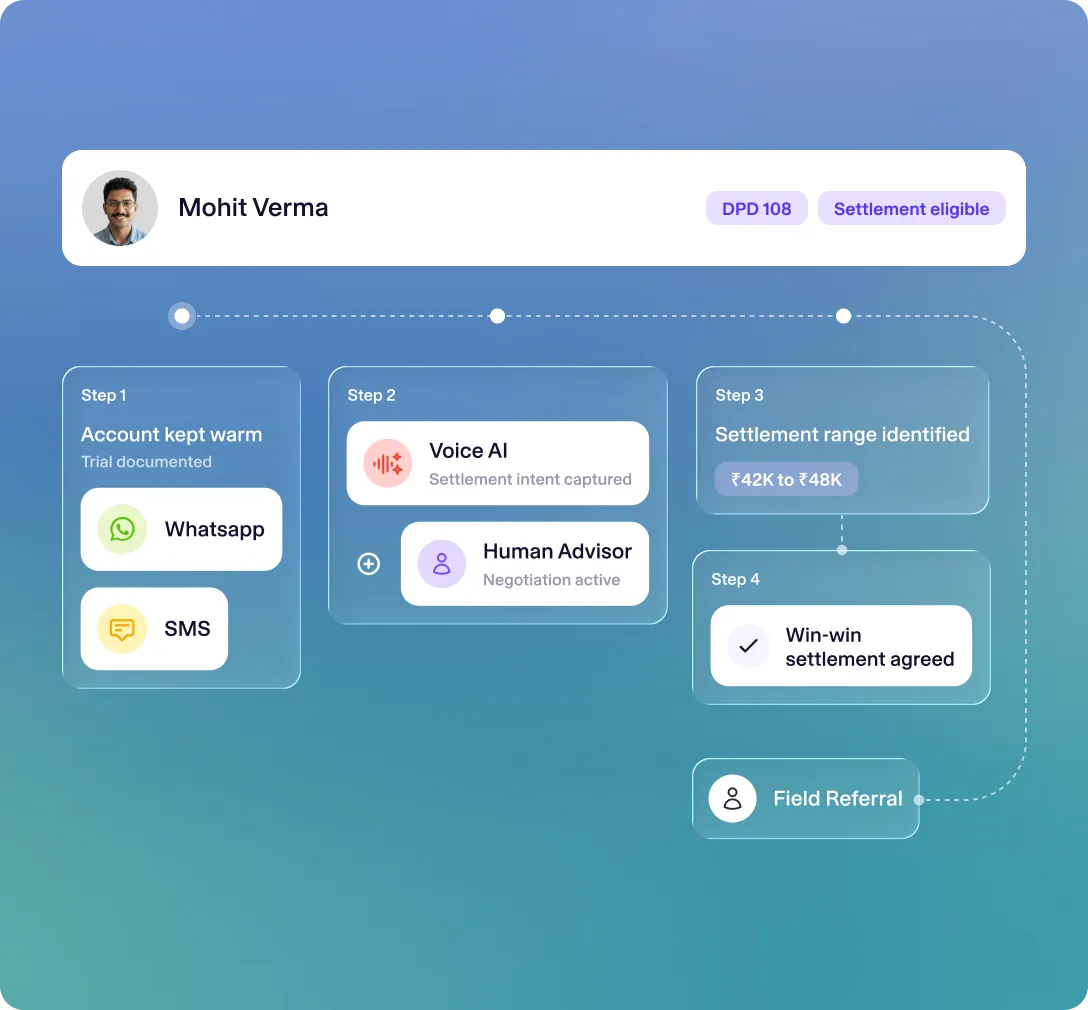
Figure out a Win-win solution.
The relationship is already strained and the alternative is legal or field cost. Digital keeps the account warm and the trail documented, while people do the closing.
Objective
Leads with
Voice AI
Human Advisors
More channels
shouldn’t mean more exposure
Scale is exactly where collections goes wrong. Every rule below is enforced before a message is sent, not audited after it lands.
Global Frequency Cap
One contact cap per borrower across all channels - not five independent ones.
Consent & DNC
Reachability preference honoured at send time. TRAI 160 series on every voice and SMS Path
Permitted Windows
Calling and messaging hours enforced by the orchestrator for every channel.
Full Audit Trail
Every message, call and transcript logged against the account. Pull any history ondemand.
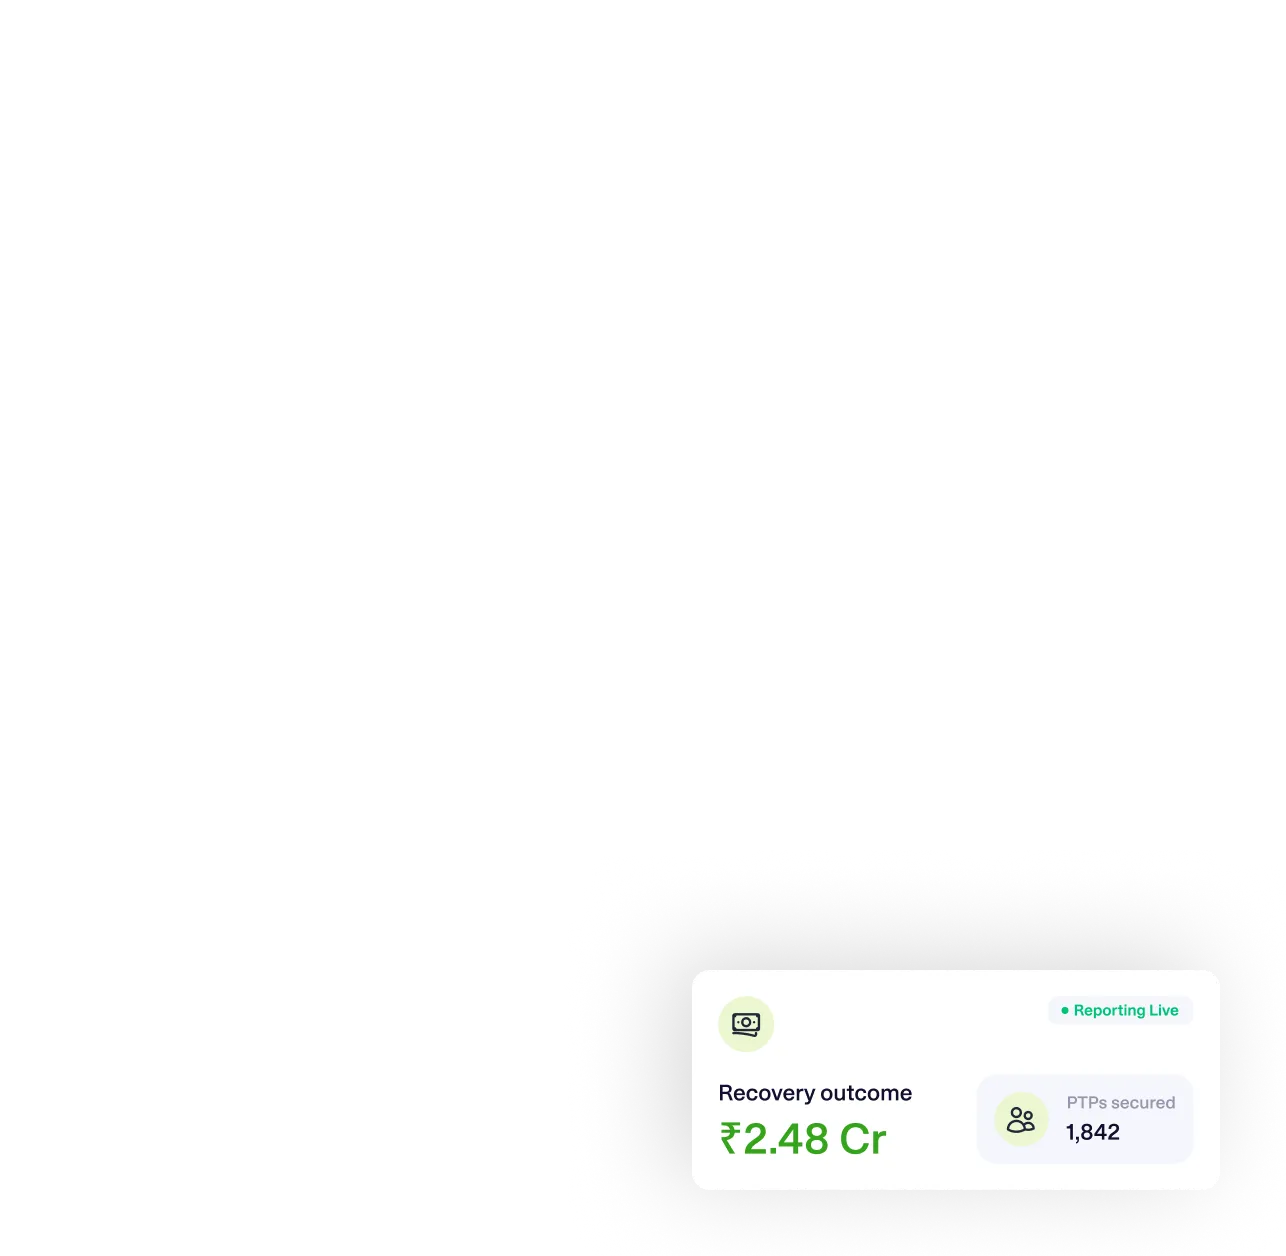
Recovery Outcomes. Delivered.
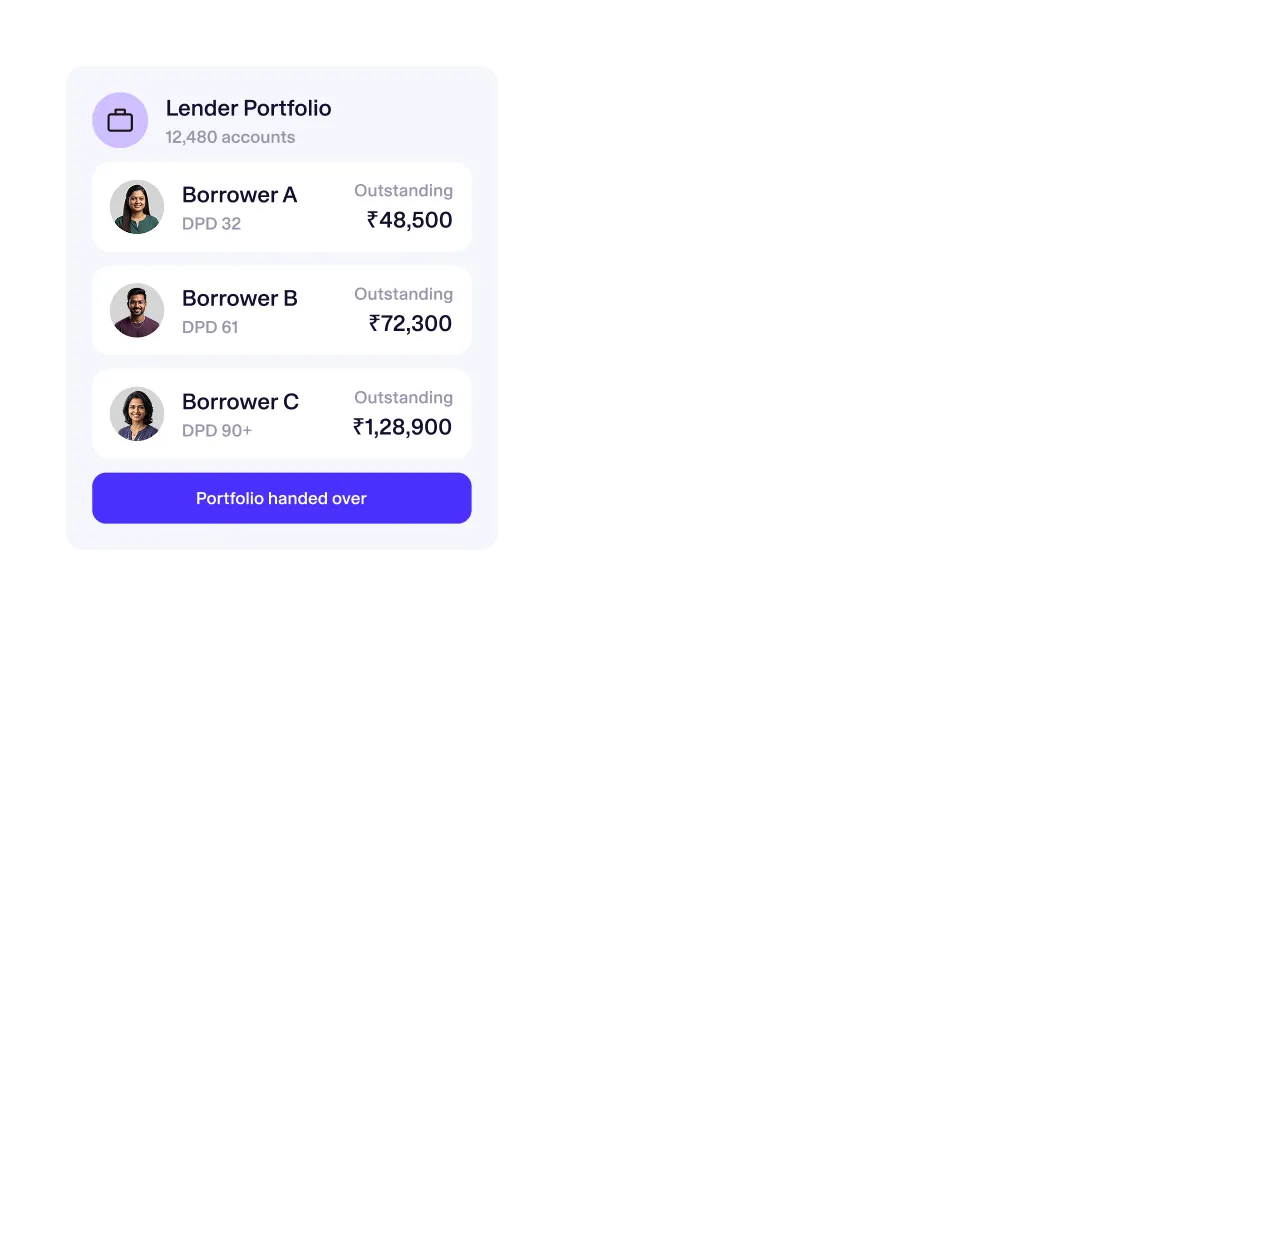
A top-10 NBFC handed over its entire unsecured PL portfolio - previously split across four agencies, four sets of reporting, and no single owner of the number
Switch to Digital Debt Collections Today for Profitable Quarter Tomorrow